
Blog
Can Google’s 9.2GWh pilot unlock new storage revenue
Estimated reading time: 5 minutes · Last updated:
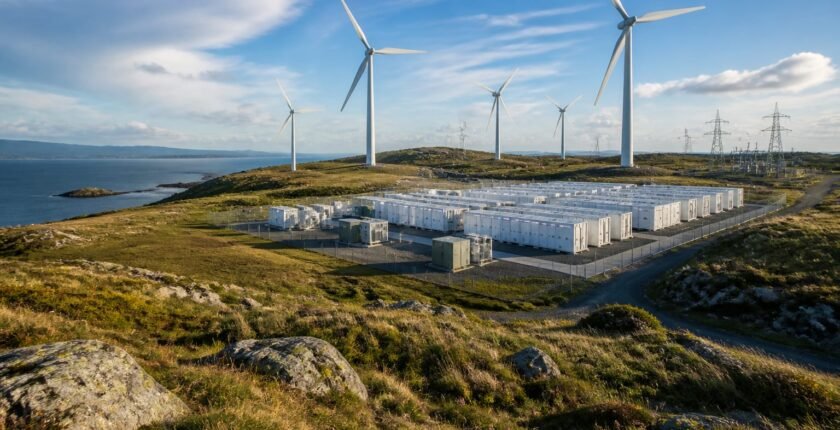
Google routed 9.2 GWh of photovoltaic charge through a storage pilot that shifted generation from midday into evening discharge, testing a method to assign hourly clean-energy attributes to hours of consumption. The trial deployed two esVolta battery sites in Texas — Anole, a 240MW/480MWh installation, and Burksol, a 100MW/200MWh installation — a combined 340MW/680MWh, and used Quintrace to verify hourly transfers under the EnergyTag standard. EsVolta remained in operational control while LevelTen Energy managed the transaction accounts. The pilot was, as first reported by pv magazine, intended to improve the hourly matching rate that Google currently reports at about 65% as it pursues 7×24 carbon-free operation by 2030.
charging at noon and discharging at night
Xingjia Shuo Energy Storage
Key takeaways
- Pilot scale: The trial shifted a total of 9.2GWh of PV charging into evening discharge using two esVolta sites totalling 340MW/680MWh.
- Verification and standards: Quintrace verified hourly charge and discharge under the EnergyTag standard while LevelTen Energy handled transaction accounting.
- Corporate drivers and deadlines: Google's hourly matching rate is about 65%, and SBTi's hourly disclosure verification opens in February 2027 for large users above 10GWh a year.
Table of contents
How the pilot assigned hours to clean power
The test used energy storage as an accounting device rather than a source of new renewable generation. esVolta charged batteries from midday photovoltaic output and discharged them into evening hours, then Quintrace applied hour-by-hour verification aligned with EnergyTag criteria to show which consumption hours could claim the shifted clean attributes. LevelTen Energy managed the bookkeeping to prevent double-counting of those attributes.
EsVolta kept operational control and the contract preserved the company's discretion to act on market prices or in grid-emergency situations outside specified delivery hours. Under that contractual design, a buyer pays for the hour-by-hour attribute transfer without acquiring the battery's dispatch rights, while the asset owner retains flexibility to provide market participation and system services.
Why this could be a new revenue stream for storage
Shifting the "time attribute" of clean energy creates a potential service that storage owners can sell: a fee for guaranteeing that a customer’s consumption hour is matched to a verified block of renewable generation. The pilot demonstrates that hourly granularity can be delivered on commercial assets without adding new generation capacity.
But monetising that service requires the storage operator to quantify additional costs: hourly metering and data governance, energy losses during round trips, and the opportunity cost of reserving state of charge for contractual delivery instead of chasing spot-market revenues at night. Contracts must set metering boundaries, loss-conversion methods and procedures for abnormal data to make the revenue legally and financially meaningful.
What firms in China need to do to compete
Domestic green-certificate systems are mostly monthly today, which limits direct participation in hourly-attribute markets. The No. 688 document and pilot programmes in Jiangxi, Jiangsu and Hunan move toward finer timescales, but storage companies must upgrade telemetry to 15-minute or hourly generation and consumption curves and implement traceability, loss accounting and certificate cancellation processes before they can offer equivalent services.
Beyond telemetry, Chinese firms should work on independent certification workflows and bilateral contracts that address cross-border recognition, because international corporate buyers and standards bodies will decide whether domestic hourly certificates satisfy frameworks such as the forthcoming GHG Protocol revision.
Regulatory milestones and corporate timing
Regulatory and standards timelines will shape the market. The SBTi Corporate Net-Zero Standard version 2.0 set out hourly matching requirements and the organisation’s verification process opens in February 2027 for large users consuming at least 10GWh a year. The GHG Protocol revision is expected to be finalised by the end of 2028, and those dates will influence whether hourly-attribute contracts become a mainstream compliance route.
Corporates aiming for full hourly carbon-free operation, like Google's 2030 7×24 target, may use storage-based attribute shifts as a bridge while long-duration resources mature. Whether that bridge becomes a scalable commercial market depends on standardised measurement, cross-system recognition and clear contract terms that allocate losses, penalties for non-delivery, and market opportunity costs.
| Project | Power (MW) | Energy (MWh) | Role in pilot |
|---|---|---|---|
| Anole | 240 | 480 | Day charge, evening discharge |
| Burksol | 100 | 200 | Day charge, evening discharge |
| Total | 340 | 680 | Combined dispatch to shift 9.2GWh |
Case for and against an hourly-attribute market
The case for
- Hourly verification creates a product that meets corporate disclosure demands and could command a premium over monthly certificates.
- Standardised verification (EnergyTag/Quintrace) and transaction accounting reduce reputational and double-counting risks, encouraging corporate buyers to pay for time-specific attributes.
The case against
- High operational costs — metering, data governance, and energy losses — may erode or eliminate the premium versus spot-market returns.
- If international frameworks like the GHG Protocol do not recognise domestic hourly certificates, cross-border demand and prices could be limited.
What to be careful about
- Attribute non-recognition: hourly certificates that are not accepted by major protocols would limit buyer demand.
- Opportunity cost: reserving SOC for contractual delivery can forfeit higher spot-market revenues at peak price hours.
- Data and metering disputes: lack of clear loss-conversion and abnormal-data rules could produce contract disputes and liability exposure.
The bottom line
The Google-backed pilot shows that storage can carry not only energy but the time-specific environmental attributes companies increasingly need for hourly carbon accounting. The technical path — high-resolution metering, loss accounting and independent hourly verification — is proven at pilot scale, but the commercial case depends on whether certificate premiums exceed the combined costs of losses, metering and foregone market revenues. Standards and recognition timelines in 2027–2028 will be decisive: if verifications and protocols accept storage-mediated hourly attributes, a new service market could emerge; if not, the model will remain a niche compliance tool.
What to watch
- Watch for SBTi's verification of hourly matching disclosures in February 2027, which will affect compliance options for large buyers.
- Watch for finalisation of the GHG Protocol revision expected by the end of 2028 and its stance on storage-mediated hourly attributes.
- Watch for expansion of provincial hourly-traceability pilots in Jiangxi, Jiangsu and Hunan; no single completion date has been set.
Frequently asked questions
What exactly did Google’s pilot move and which assets were used?
The pilot mobilised two esVolta storage sites in Texas — Anole (240MW/480MWh) and Burksol (100MW/200MWh), together 340MW/680MWh — and shifted 9.2GWh of PV charging from midday to evening discharge while Quintrace verified the hourly transfers.
How does hourly matching differ from traditional renewable certificates?
Traditional certificates are typically monthly or annual and cannot prove that a specific hour of consumption matched a specific hour of generation; hourly matching uses per-hour verification (the pilot used EnergyTag criteria verified by Quintrace) to assign clean attributes to individual consumption hours.
Will Chinese hourly certificates be accepted internationally?
That is uncertain: the WeChat analysis notes domestic pilots in Jiangxi, Jiangsu and Hunan and regulatory moves such as No. 688, but international recognition depends on whether frameworks like the GHG Protocol (expected finalisation by end of 2028) accept those local systems.
Related reading